Your exact plan for leaving SAVE, in writing
The calculator gives you the payment. The report gives you the decision: which plan to pick on your numbers, what you’ll pay in total, the traps that apply to you, and the exact steps.
What’s inside
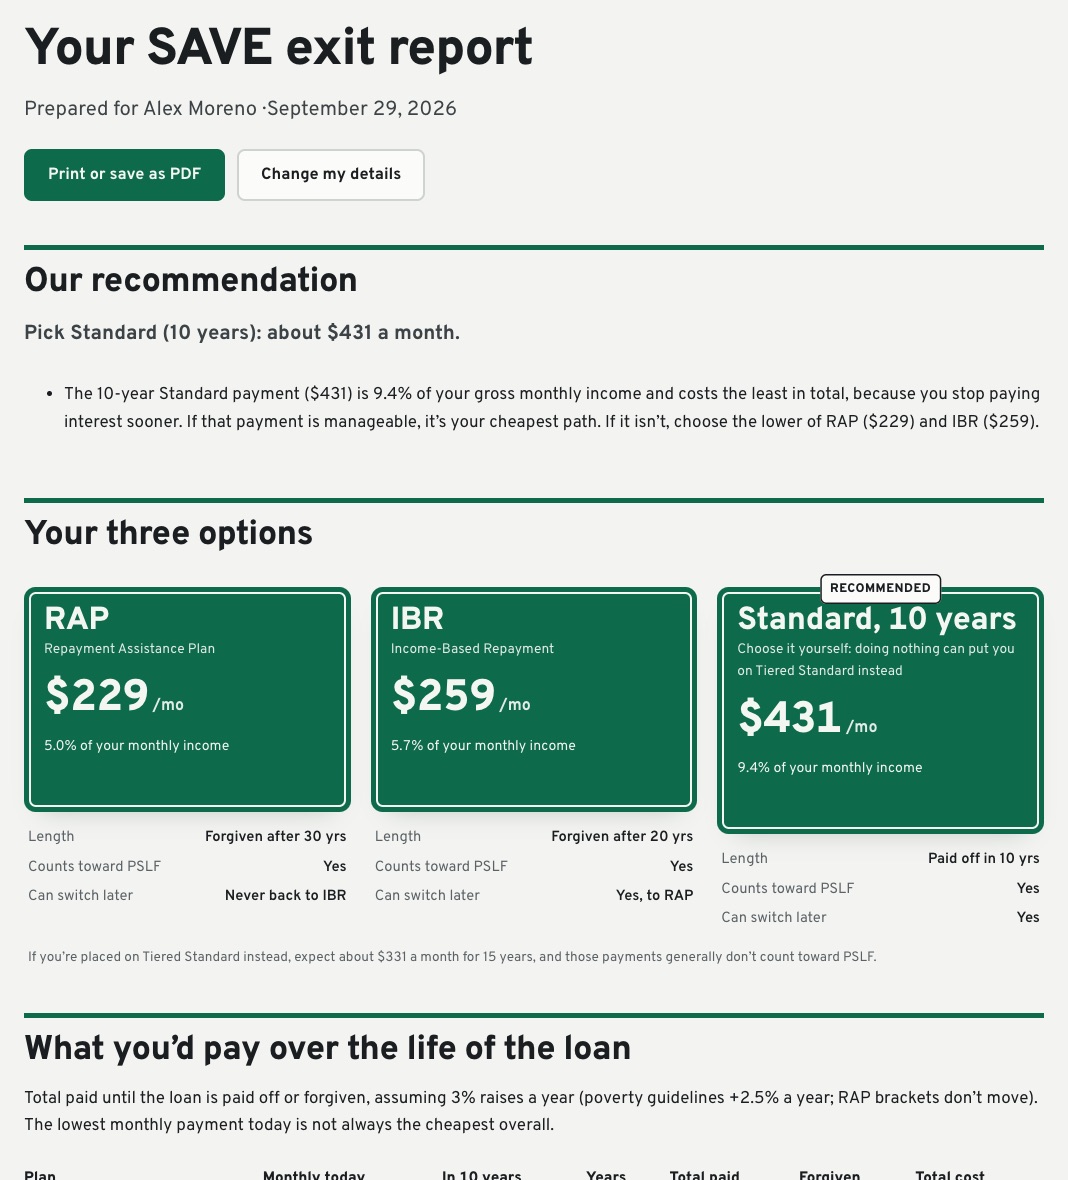
- Your recommendation, with the reason
- Which plan to pick for your income, family and goals, and why, in plain words.
- Your lifetime cost on every plan
- Monthly payment, years, total paid and amount forgiven on RAP, IBR, Standard and Tiered Standard.
- Married? File together or separately
- What your payment would be if you filed separately, so you can weigh it against the tax cost.
- PSLF check
- Payments left, what’s forgiven tax-free, and the plans that would cost you credit.
- The traps that apply to you
- The 2028 IBR cutoff, the one-way RAP switch, Tiered Standard and PSLF, checked against your case.
- Step-by-step on studentaid.gov
- What to have ready, what to pick, and how to prove you applied in time.
- Three letters, filled in
- To your servicer if the plan is applied wrong or your application stalls, and a complaint to the FSA Ombudsman.
- Your deadline in your calendar
- A calendar file with reminders 14 days and 2 days before your date.
Why the lowest payment isn’t always the best
Sample · fictional borrower
What you’d pay in total on each plan
Here RAP gives the lowest payment ($229 a month), but paying the Standard plan over 10 years ($431 a month) costs $10,196 less in total. The report explains which one fits you, and why.
What we never do
- Ask for your FSA ID or password.
- Apply for plans on your behalf or talk to your servicer.
- Promise you loan forgiveness.
The FTC warns against companies that charge up front to “handle” student loans.1 This is something else: a report you read, and a switch you make yourself, free, on studentaid.gov.2
Questions about buying
Do I need to pay to switch plans?
No. Switching is free at studentaid.gov and our calculator is free. The report is for people who want the decision explained and everything in writing.
How do I get the report?
After paying you return to this site and the report is built instantly from your numbers. Print it or save it as a PDF, and reopen it from the link in your receipt.
Do you store my information?
No. The numbers you type stay in your browser. Stripe processes the payment; we only see that it was paid and the receipt email.
Is this financial advice?
No. It’s an educational estimate using the official 2026 formulas. Your servicer calculates the official payment.
What if it doesn’t help me?
Email us within 14 days of purchase and we’ll refund you, no questions asked.
Sources
- Student loan scammers won’t offer relief Federal Trade Commission · Official source
- Income-Driven Repayment Plan application Federal Student Aid (studentaid.gov) · Official source