Lowest payment
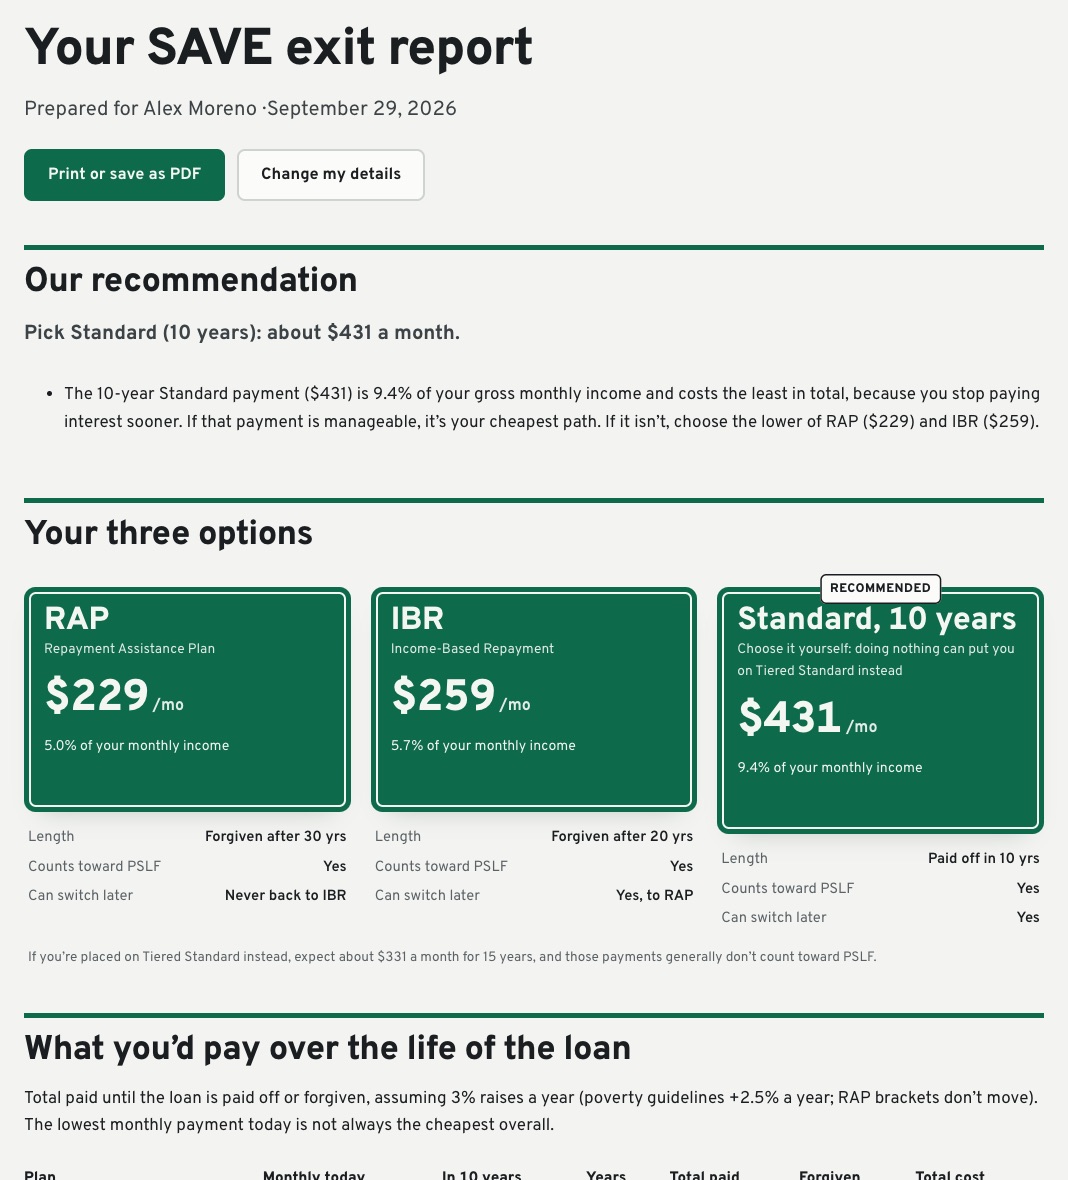
RAP
Repayment Assistance Plan
/mo
5.0% of your monthly income
- Length
- Forgiven after 30 yrs
- Counts toward PSLF
- Yes
- Can switch later
- Never back to IBR
- Deadline to choose
- Open any time
Your RAP payment in a minute, side by side with IBR. Free, no sign-up.
Enter your AGI and balance: you’ll see your payment on RAP, on IBR, and on the plan you get if you don’t choose, using the 2026 federal formulas.
Showing an example borrower: $55,000 income, single, $38,000 at 6.5%. Enter your numbers to see yours.
Lowest payment
Repayment Assistance Plan
/mo
5.0% of your monthly income
Lowest payment
Income-Based Repayment
/mo
5.7% of your monthly income
Lowest payment
Standard plan, assigned automatically
/mo
9.4% of your monthly income
Or $331/mo on Tiered Standard (15 yrs, no PSLF credit).
Estimates from the 2026 federal formulas. Your servicer calculates the official amount.
Your report tells you which plan to pick with your numbers, what to watch for, and the exact steps. Instant and printable.
$29 one time
Secure checkout by Stripe. Card, Apple Pay or Google Pay. 14-day money-back guarantee. If it doesn’t help, email us for a full refund.
On top of that, if your payment doesn’t cover the month’s interest, the rest of the interest is waived, and if your principal drops by less than $50 in a month, the government makes up the difference up to $50. After 360 payments (30 years), what’s left is forgiven, and that forgiveness is federally taxable.1,2
| AGI | RAP rate | RAP, single | RAP, couple + 2 kids | IBR, couple + 2 kids |
|---|---|---|---|---|
| $25,000 | 2% | $42 | $10 | $0 |
| $40,000 | 3% | $100 | $10 | $0 |
| $55,000 | 5% | $229 | $129 | $46 |
| $75,000 | 7% | $438 | $338 | $213 |
| $100,000 | 9% | $750 | $650 | $421 |
Look at the last column: with kids and a joint return, IBR is often cheaper than RAP because it protects 150% of your household’s poverty line.3 RAP vs IBR: which is right for you.
File jointly and RAP uses both incomes. File separately and it uses only yours, which can cut the payment a lot in exchange for higher taxes. If you both have loans and file jointly, the household payment is split by what each of you owes.2 Married filing separately on RAP or IBR.
$29 one time
Which plan to pick and why, what you’ll pay in total, whether filing separately saves you money, PSLF, the steps on studentaid.gov, and ready letters if your servicer gets it wrong.
See the report14-day money-back guarantee. Switching is free at studentaid.gov: we sell clarity, never the paperwork.